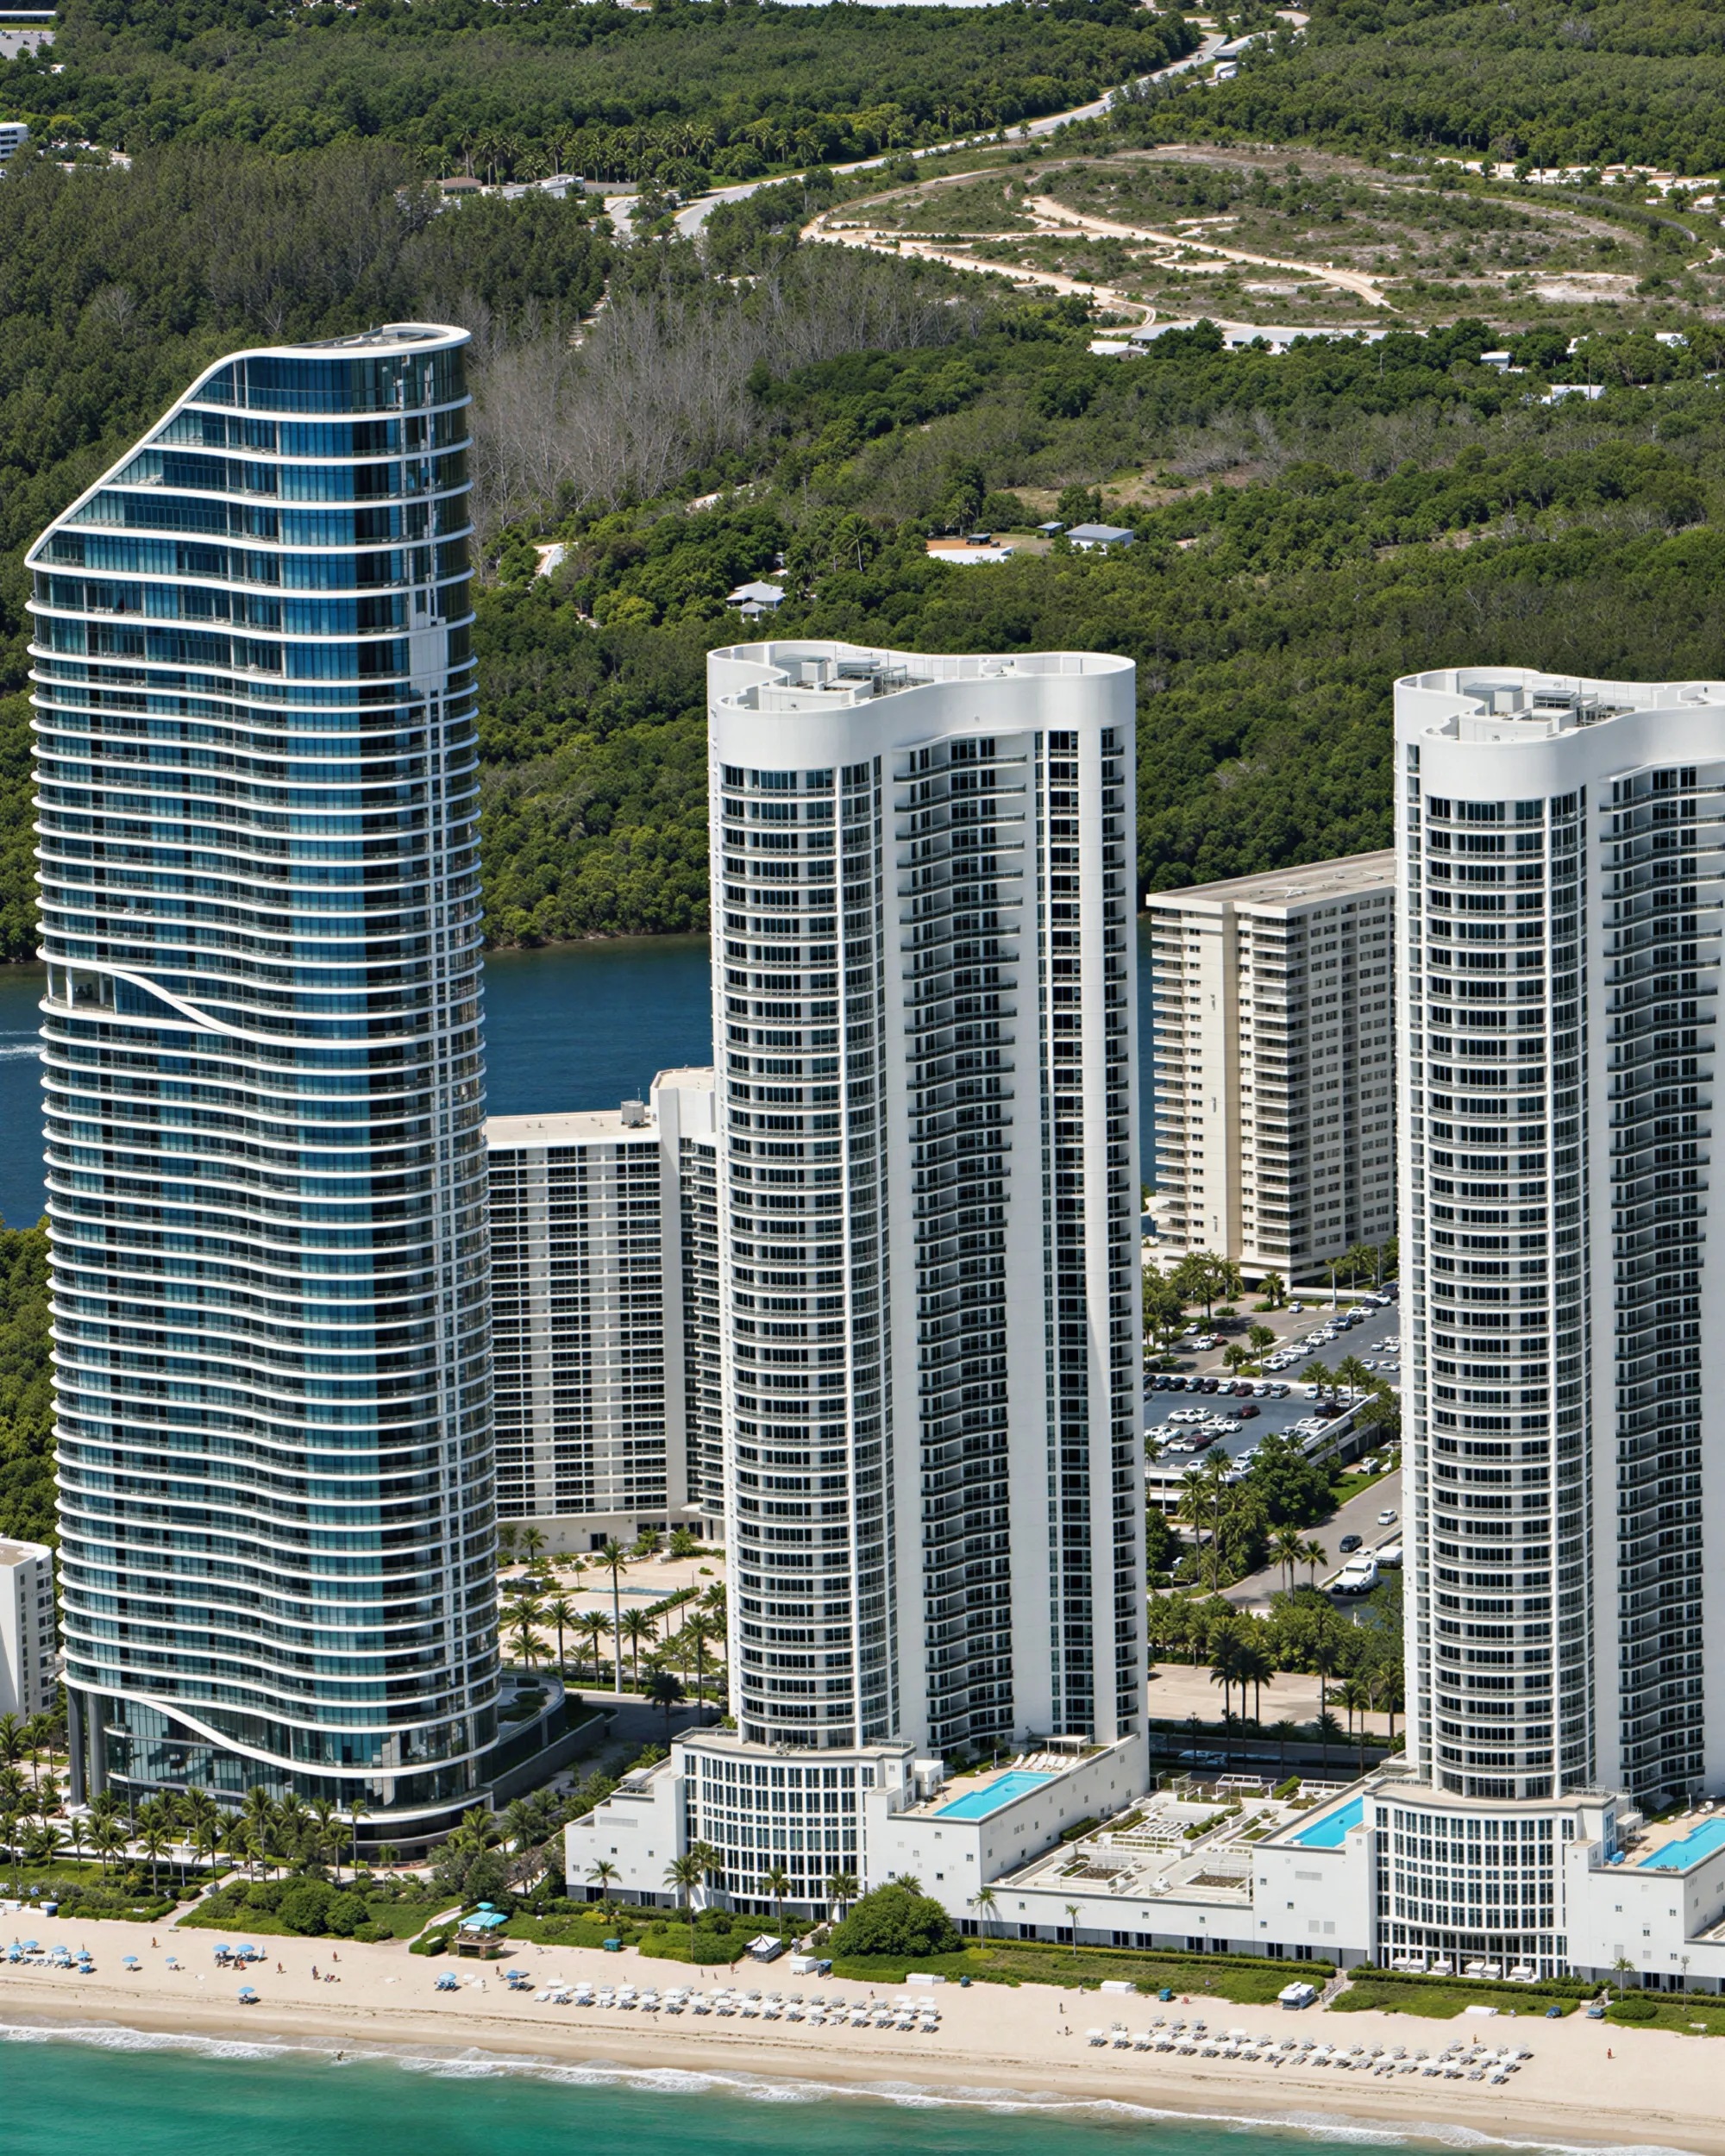
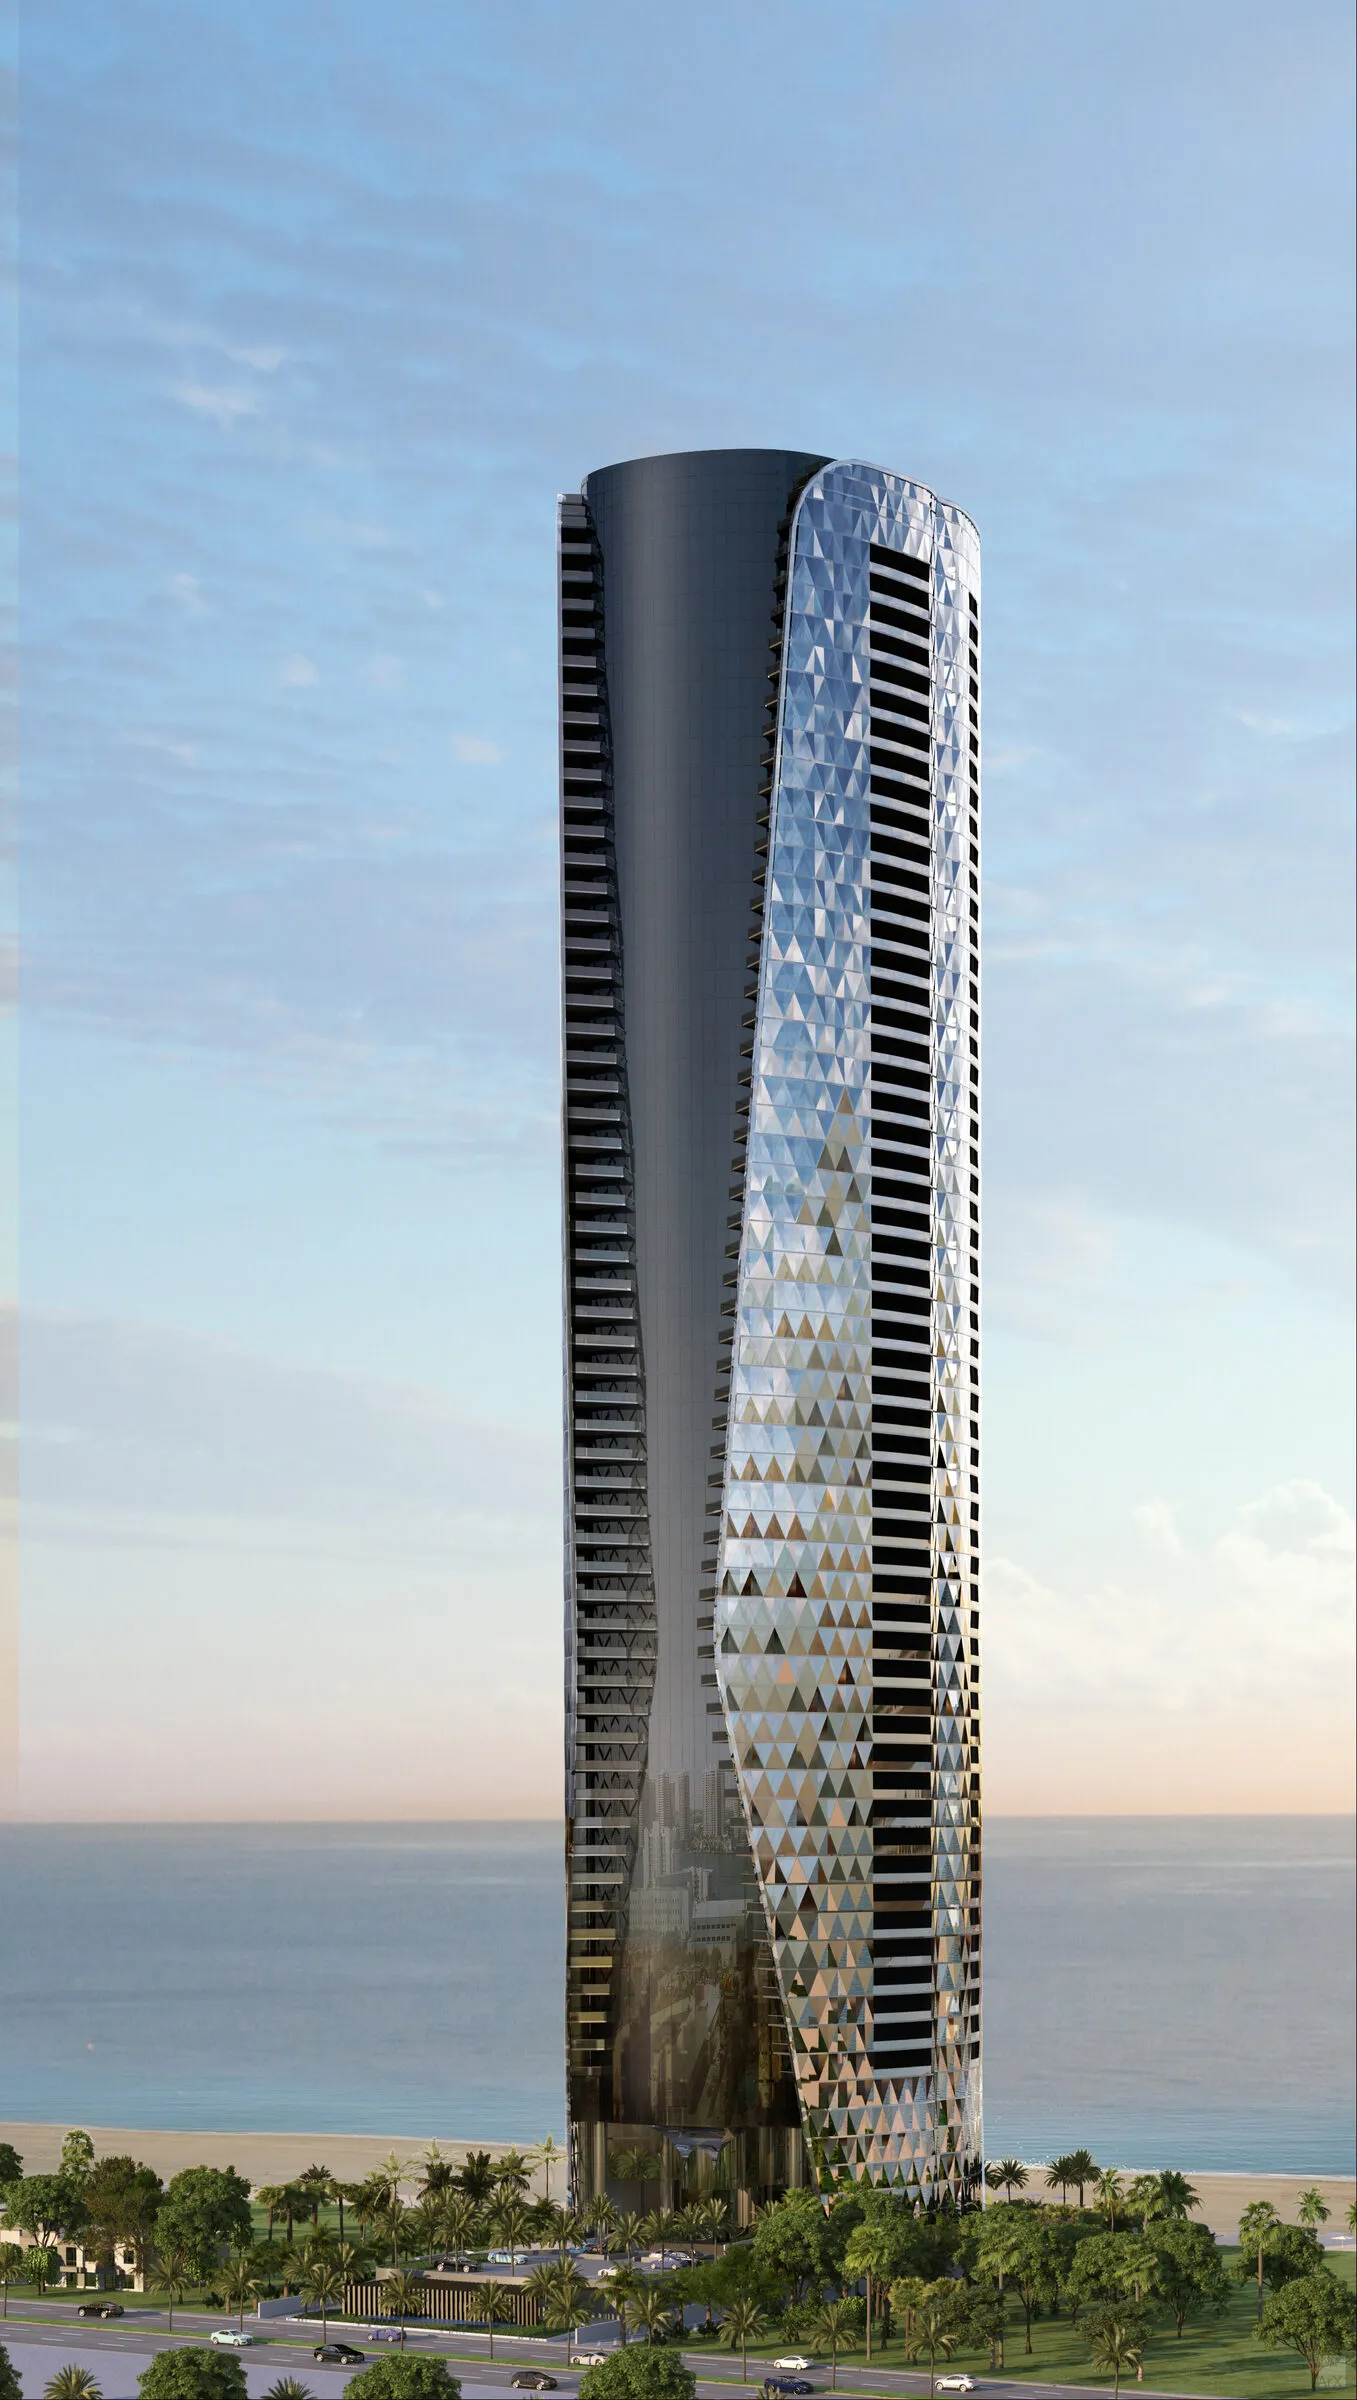
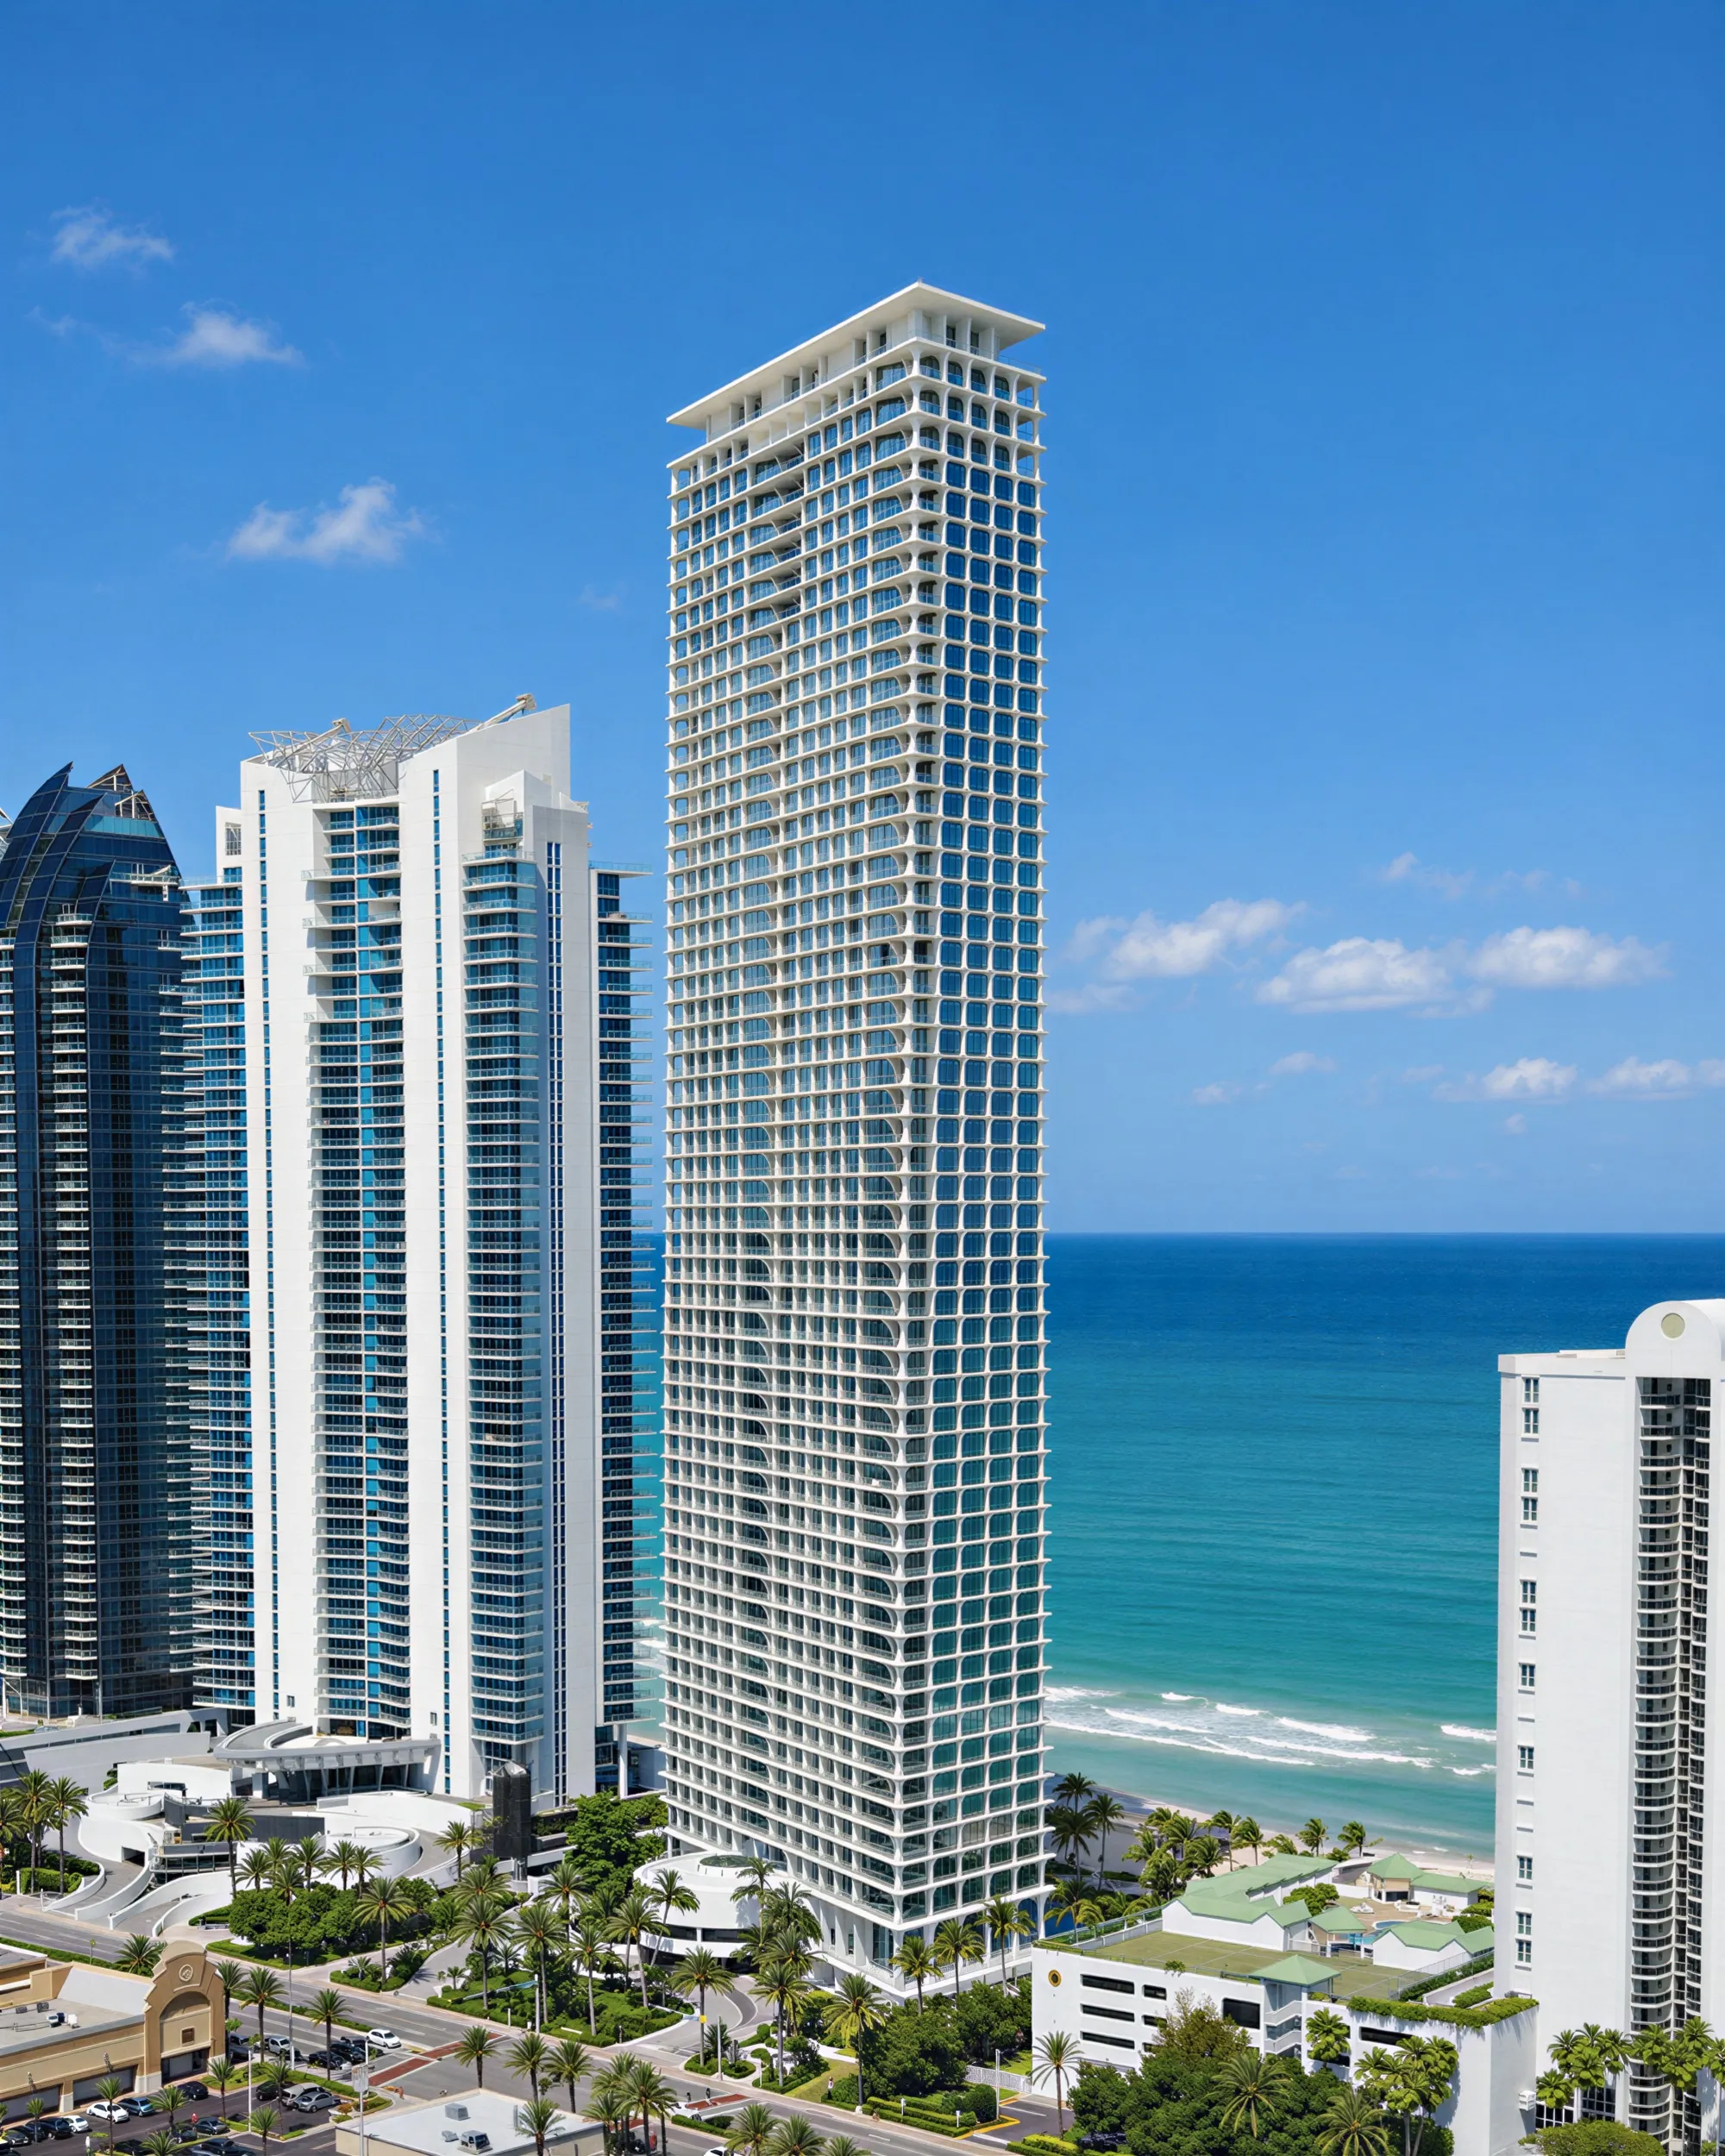
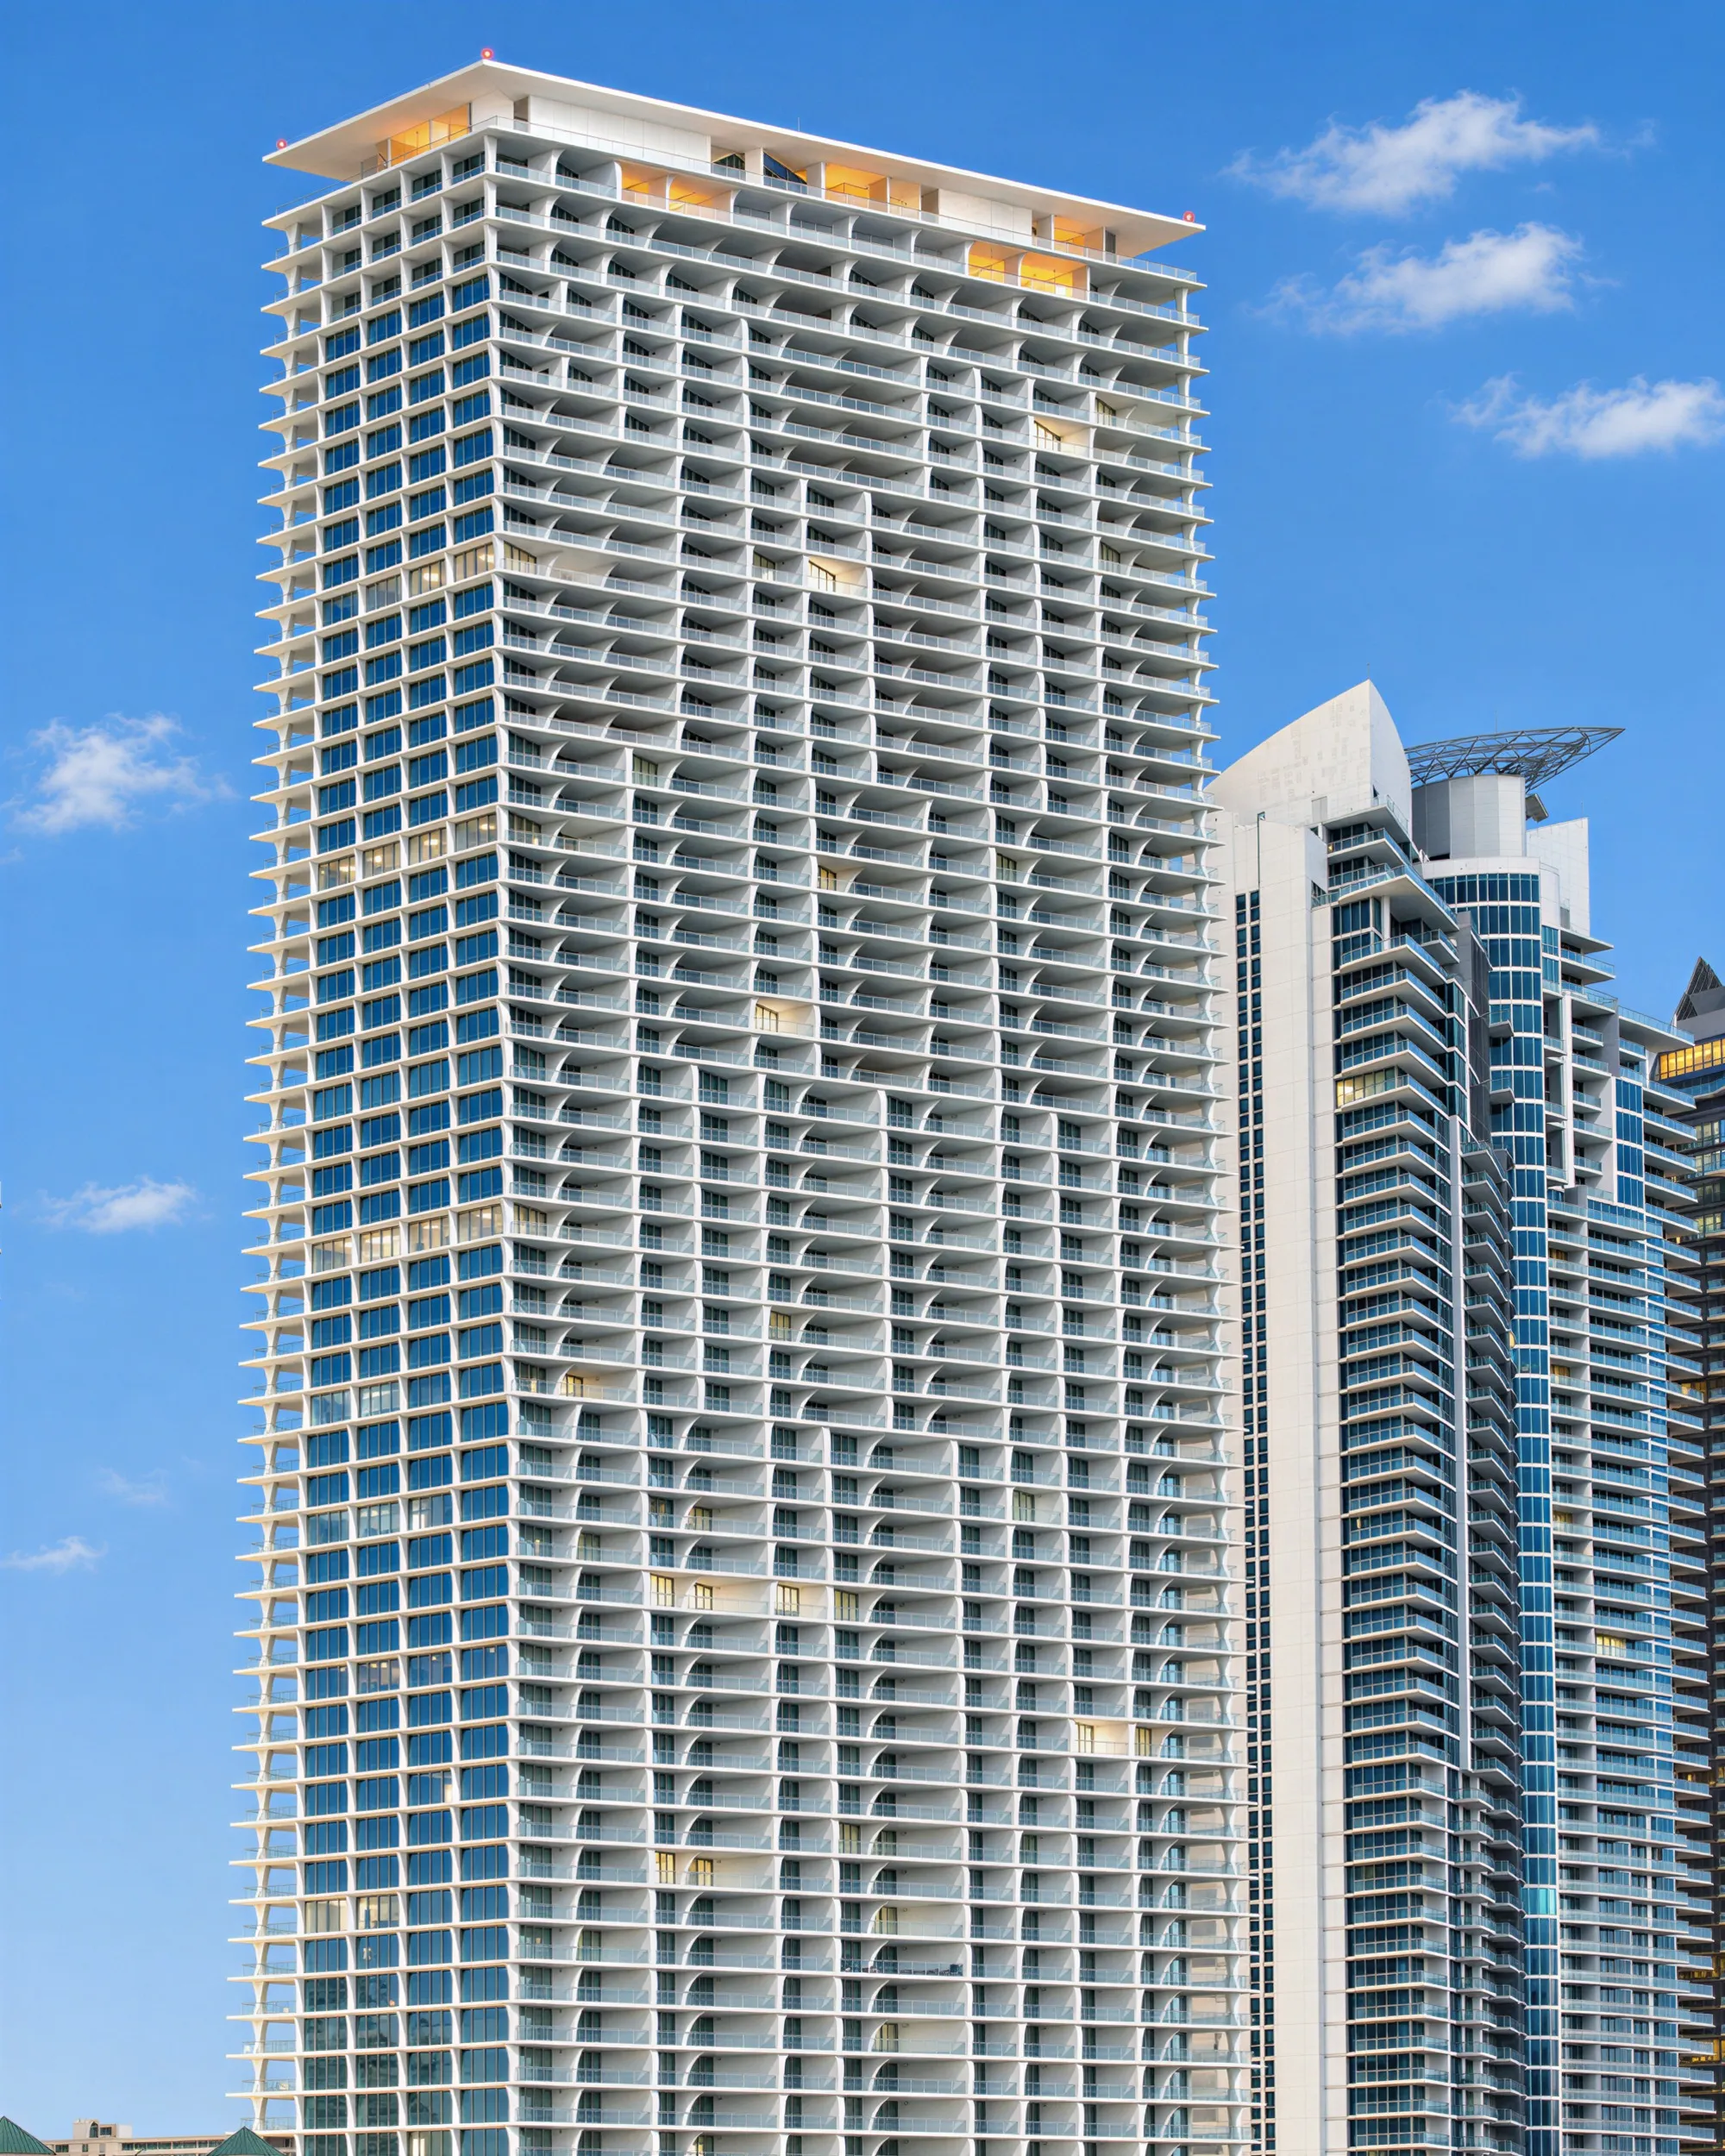
On both FEMA maps, today's and the one that takes effect in 2027, the tower stands in Zone X (unshaded): outside the area with a 1% chance of flooding in any year, where flood risk is minimal. The change is on the beach side.
Today's maps, in force since 11 September 2009, cross three bands toward the sea. Zone X (shaded) has a 0.2% annual chance of flooding. Zone AE, the 1% annual-chance area where a mortgage lender usually requires flood insurance, has a base flood elevation of 8 feet (2.4 m). At the beach, Zone VE, where storm waves strike and building rules are strictest, stands at 10 feet (3.0 m).
A base flood elevation is the height the water would reach in a 1%-a-year flood, measured from the map's reference level (NGVD29 on the current maps); it is never a depth of water above the ground.
The revised maps take effect on 19 February 2027. They keep the building in Zone X (unshaded) and the beach in Zone VE, at 10 feet measured from a newer reference level (NAVD88). Between the two they draw Zone AO, an area of shallow flooding where the figure is the expected depth of water: 3 feet (0.9 m) here. The VE line moves some 50 meters closer, to about 50 meters east of the building instead of about 100 today. These are readings of FEMA's National Flood Hazard Layer, not official flood-zone determinations.
Like all of Sunny Isles Beach and Golden Beach, the address lies in Miami-Dade Storm Surge Planning Zone B: storm surge, the sea water a hurricane pushes ashore, is a risk from Category 2 storms upward. The county orders evacuations by each storm's track and projected surge, not by category alone.
Flood insurance. The National Flood Insurance Program (NFIP) covers up to $250,000 for a residential building and $100,000 for contents. An association's building policy covers at most $250,000 per unit, or the building's replacement cost if that is lower: $48 million for the 192 units in the recorded condominium. At these values, cover above those limits is bought privately.
Windstorm insurance. Citizens, Florida's state-backed insurer of last resort, may not write a unit owner's policy where the combined replacement cost of the unit's dwelling and contents is $700,000 or more. The threshold rises to $1 million in counties where the state insurance regulator finds too little competition. What counts is that replacement cost, not the price paid; the association insures the building separately. An insurance agent can say whether a given unit qualifies.
 The
 Turnberry
 The
 Muse